Debbie Rewards

- 3.95K Reviews
- 4.9
- Downloads
- 100,000+
 Analysis by Mobxio
I look at Debbie Rewards as a finance app with a simple promise: help users pay off, save, and earn through rewards. That idea can be appealing if you want everyday spending to feel more purposeful, but the real value depends on how the app’s reward process fits your habits. I would approach it as a possible extra tool for managing money, not as a replacement for a budget, savings account, or debt plan.
Before deciding whether it belongs in your routine, I’d separate two questions: does the app cost anything to try, and does its reward approach actually help with your particular goal? The first is straightforward; the second depends on how clearly you understand the actions involved and whether the incentive supports a plan you would follow anyway.
What the free price does—and does not—tell you
Debbie Rewards is free to download and use, which makes trying it a lower-commitment decision than signing up for a paid finance service. Debbie Inc. is the developer, and the app sits in the personal-finance space rather than functioning as a general shopping or entertainment app. Its listed age rating is Everyone, so it is presented for a broad audience.
Free access is a meaningful part of the value proposition, but it is not the same as a guarantee that every possible activity or benefit has no conditions. I would read the in-app explanations carefully before changing a financial routine around rewards. In particular, check what actions qualify, how rewards are earned or applied, and whether there are any steps you must complete before a benefit becomes useful. Those details matter more than the word “free” when deciding whether an app can help with a real financial goal.
The app has an average rating of 4.9 from around 15,000 ratings, with roughly 3,900 written reviews, and it has passed 100,000 installs. Those figures suggest that plenty of people have tried it and that user response is strong. They are useful context, not proof that the app will suit every financial situation or that every user gets the same outcome.
Where the value can come from
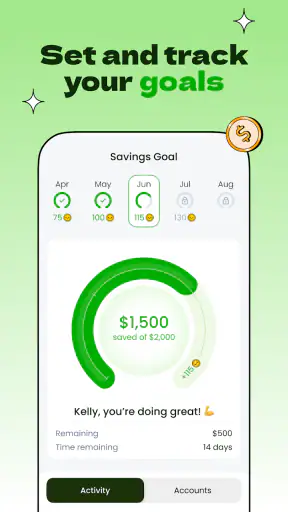
The most interesting idea here is the connection between rewards and financial progress. Many money apps focus on recording transactions, setting a budget, or moving cash into savings. Debbie Rewards is framed around the possibility of earning while working toward paying off debt or saving. That can make the experience feel more motivating than a tracker that only tells you where your money went.
Still, I would judge the value by the usefulness of the reward in your own circumstances, not by the excitement of earning something. If you are already making a regular payment toward a balance, for example, a reward linked to that kind of activity may feel like a small nudge to keep your routine going. It should not persuade you to spend more, take on new debt, or delay a payment that matters. A reward is most helpful when it supports a decision you already consider financially sensible.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
A practical way to test the app is to choose one clear goal before you start. You might be trying to build a saving habit or stay consistent with paying down a balance. Then use Debbie Rewards alongside your usual records for a short period and ask whether it makes the next step easier to remember or complete. This avoids treating a growing reward balance as the goal in itself.
A realistic way to fit it into a routine
Imagine you review your finances on payday and decide how much to put toward a balance and how much to keep for upcoming expenses. You could check Debbie Rewards during that same review, see whether it offers a relevant way to support the plan, and record the actual payment or saving separately in your regular account records. That last step is useful because rewards and cash flow are not automatically the same thing: your budget should still reflect money you can actually spend.
I would also avoid checking the app every time you make a small purchase. That can turn a helpful financial prompt into another distraction and make it harder to tell whether rewards are changing your habits. A weekly or payday check-in is a more deliberate workflow: review the goal, confirm what you have done, and decide whether the app is adding anything beyond the routine you already follow.
One non-obvious trade-off is attention. An app that makes rewards visible may encourage consistency, but it can also pull your focus toward earning rather than the total cost of a financial choice. Before taking any action prompted by a reward, compare it with what you would have done without the incentive. If it leads you to spend more or rearrange a payment in a way that costs you elsewhere, the reward may not be worth pursuing.
Where it differs from familiar finance tools
A standard budgeting app is usually the better choice when your main need is a detailed picture of income, bills, and spending categories. A bank’s own tools may be more convenient for checking balances and managing payments in one place. A spreadsheet can be better if you want full control over how you track debt and savings. Debbie Rewards appears most relevant when the reward angle is itself useful to your motivation, rather than when you need the broadest possible set of money-management tools.
That distinction matters if you already have a system that works. You do not need to replace it just because a separate app offers rewards. Instead, consider whether Debbie Rewards can sit beside your current approach without duplicating work. If you find yourself entering the same information in several places or checking multiple apps to understand one goal, the extra friction may outweigh the motivational benefit.
I would treat it as a companion rather than a financial source of truth. Keep important payment dates, balances, and savings targets in whichever service or record you already trust for those jobs. Use Debbie Rewards only for the part it handles well for you: connecting a reward-oriented experience with the goals of paying off or saving.
Small habits that make a fair test
Before relying on any reward, read the relevant terms inside the app and make sure you understand the sequence from qualifying action to usable benefit. That is a better approach than assuming that seeing a reward means it is already available to spend. If the steps feel confusing, pause and clarify them before building a plan around them.
Keep your first goal narrow. Trying to monitor several balances, savings targets, and spending habits at once makes it hard to tell what is working. Pick one area, note your normal routine, and see whether the app makes that routine easier to maintain. This gives you a useful comparison without requiring elaborate tracking or a major change to your finances.
It is also sensible to check whether the app remains useful after the novelty wears off. A reward can make the first few check-ins feel engaging, but lasting value comes from helping you follow through. If you stop opening it and your habits are unchanged, there is little reason to keep it in your routine simply because its download was free.
Who is likely to get the most from it
I can see Debbie Rewards working best for someone who already wants to save or pay down debt and responds well to small incentives. It may also suit people who find ordinary finance trackers dull and would welcome a reason to revisit a goal regularly. The key is having a goal that makes sense without the reward; the app should reinforce it, not define it.
It is less suitable if you need comprehensive budgeting, investment research, account management, or detailed debt-planning tools from a single service. It is also a poor fit if rewards tempt you into unnecessary spending or if you prefer to keep all financial activity inside your bank’s own app. In those cases, a conventional budget tracker, a direct bank tool, or a simple written plan may be easier to trust and maintain.
There is another useful exception: if you are dealing with urgent bills or unstable cash flow, focus first on understanding what is due and when. Rewards should not distract from essentials or make a difficult financial decision seem easier than it is. The app’s appeal is strongest when you have room to build a habit, not when an incentive risks obscuring a pressing priority.
What to expect from the app itself
Debbie Rewards launched on February 15, 2023, and its current version is 2.6.36. It requires Android 7.0 or later. I mention those details because they help you decide whether it is compatible with your device and whether you are looking at the current release, but they do not change the main question: does the reward approach help you make progress in a way you can sustain?
With its high average rating and substantial number of users, the app has attracted a positive response. I would take that as a reason to consider giving it a fair try, while remembering that ratings cannot tell you how well its particular reward process matches your goals. Your own test should focus on clarity, convenience, and whether the app supports better financial follow-through without adding more work.
For a practical first session, I would avoid trying to set up an elaborate system. Start by identifying the one goal you want the app to support, then read the screens that explain how rewards relate to that goal. If the process makes sense, keep your normal budget or bank record open as the reference point and note any action you take outside the app. This makes it easier to distinguish a useful prompt from a change that merely feels productive because it involves another screen.
It is also worth asking whether you want an incentive at all. Some people follow through better when progress has a visible reward; others prefer a quiet, predictable routine with no extra prompts. If you belong to the second group, a recurring calendar reminder or a simple note beside your budget may be less distracting. Debbie Rewards has a clearer case when the reward mechanism adds motivation you do not already get from your existing method.
My buy-or-skip verdict
For a free finance app, the strongest reason to try Debbie Rewards is its focus on making saving or paying off debt feel more motivating. I would start with one modest goal, learn exactly how the reward steps work, and keep my usual financial records in place. If the app helps you stay consistent without encouraging extra spending, it can earn a spot in your routine.
I would skip it if you expect a full budgeting system, want every money task handled in one place, or find reward prompts distracting. The free price lowers the cost of testing it, but your time and attention still count. My recommendation is a cautious yes for goal-minded users who enjoy incentives, and a pass for anyone whose current bank or budgeting setup already does the job cleanly. Debbie Inc.’s Debbie Rewards is most convincing when it acts as a useful nudge—not when you rely on rewards to do the work of a sound financial plan.
Debbie Rewards FAQ
What is Debbie Rewards, and how does it work?
Debbie Rewards is presented as a rewards app, but the exact earning activities and redemption options can vary by country and by the version available in your app store. Before signing up, check the app listing and its in-app terms to confirm which offers are currently available to you. Review any eligibility rules carefully, since rewards may depend on completing specified actions rather than simply installing the app.
Is Debbie Rewards free to download and use?
The app may be free to download, but that does not necessarily mean every feature or offer is cost-free. Some rewards programs require purchases, subscriptions, or other qualifying actions, and mobile data charges may also apply. Read the offer details before participating, and check the app-store listing for any disclosed in-app purchases. Avoid assuming that an advertised reward is guaranteed until you have reviewed its conditions.
How can I redeem rewards in Debbie Rewards?
Redemption methods, minimum balances, and processing times should be confirmed in the app, because they can change and may differ by region. Look for a rewards or withdrawal section that explains how to qualify, what information is required, and whether a reward can expire. Keep records of completed offers and follow the stated instructions. If a redemption does not appear, consult the app’s official support channels rather than sharing account details with unofficial sources.
What personal information does Debbie Rewards collect?
The information collected can depend on the app’s features, your device, and the privacy practices in effect when you install it. Review the privacy policy and the data-safety information on the relevant app-store page before creating an account. Pay particular attention to requested permissions, advertising or analytics data, and whether information may be shared with service providers. Grant only permissions that make sense for the features you intend to use.
Is Debbie Rewards available on Android and iOS, and how can I stay safe?
Availability can differ by country, device, and app-store listing, so search for Debbie Rewards in the official Google Play Store or Apple App Store and verify the developer before downloading. Do not install files from unfamiliar websites or trust messages promising guaranteed earnings. Use a strong, unique password if an account is required, read offer terms before completing tasks, and contact official support if you encounter suspicious requests or unexpected charges.
The Best Parts of Debbie Rewards
Things to Keep in Mind About Debbie Rewards